Loading The Mortgage PeopleA better way to Home
Case studies

A clearer, more human way to think about common mortgage decisions.

These are illustrative examples. They are designed to make the trade-offs easier to understand, not to replace personalised advice.

Is HDB loan better? How much could you save and invest?
Home and mortgage rate comparison

Plenty of homeowners like the familiarity of the HDB concessionary loan. That comfort matters. But this example asks a practical question: if a homeowner kept refinancing into suitable bank packages that tracked close to SORA over time, what would the long-run difference look like?

Illustrative HDB level2.6%
Illustrative bank pathAvg 1.585%
Estimated interest gap~S$74.6k
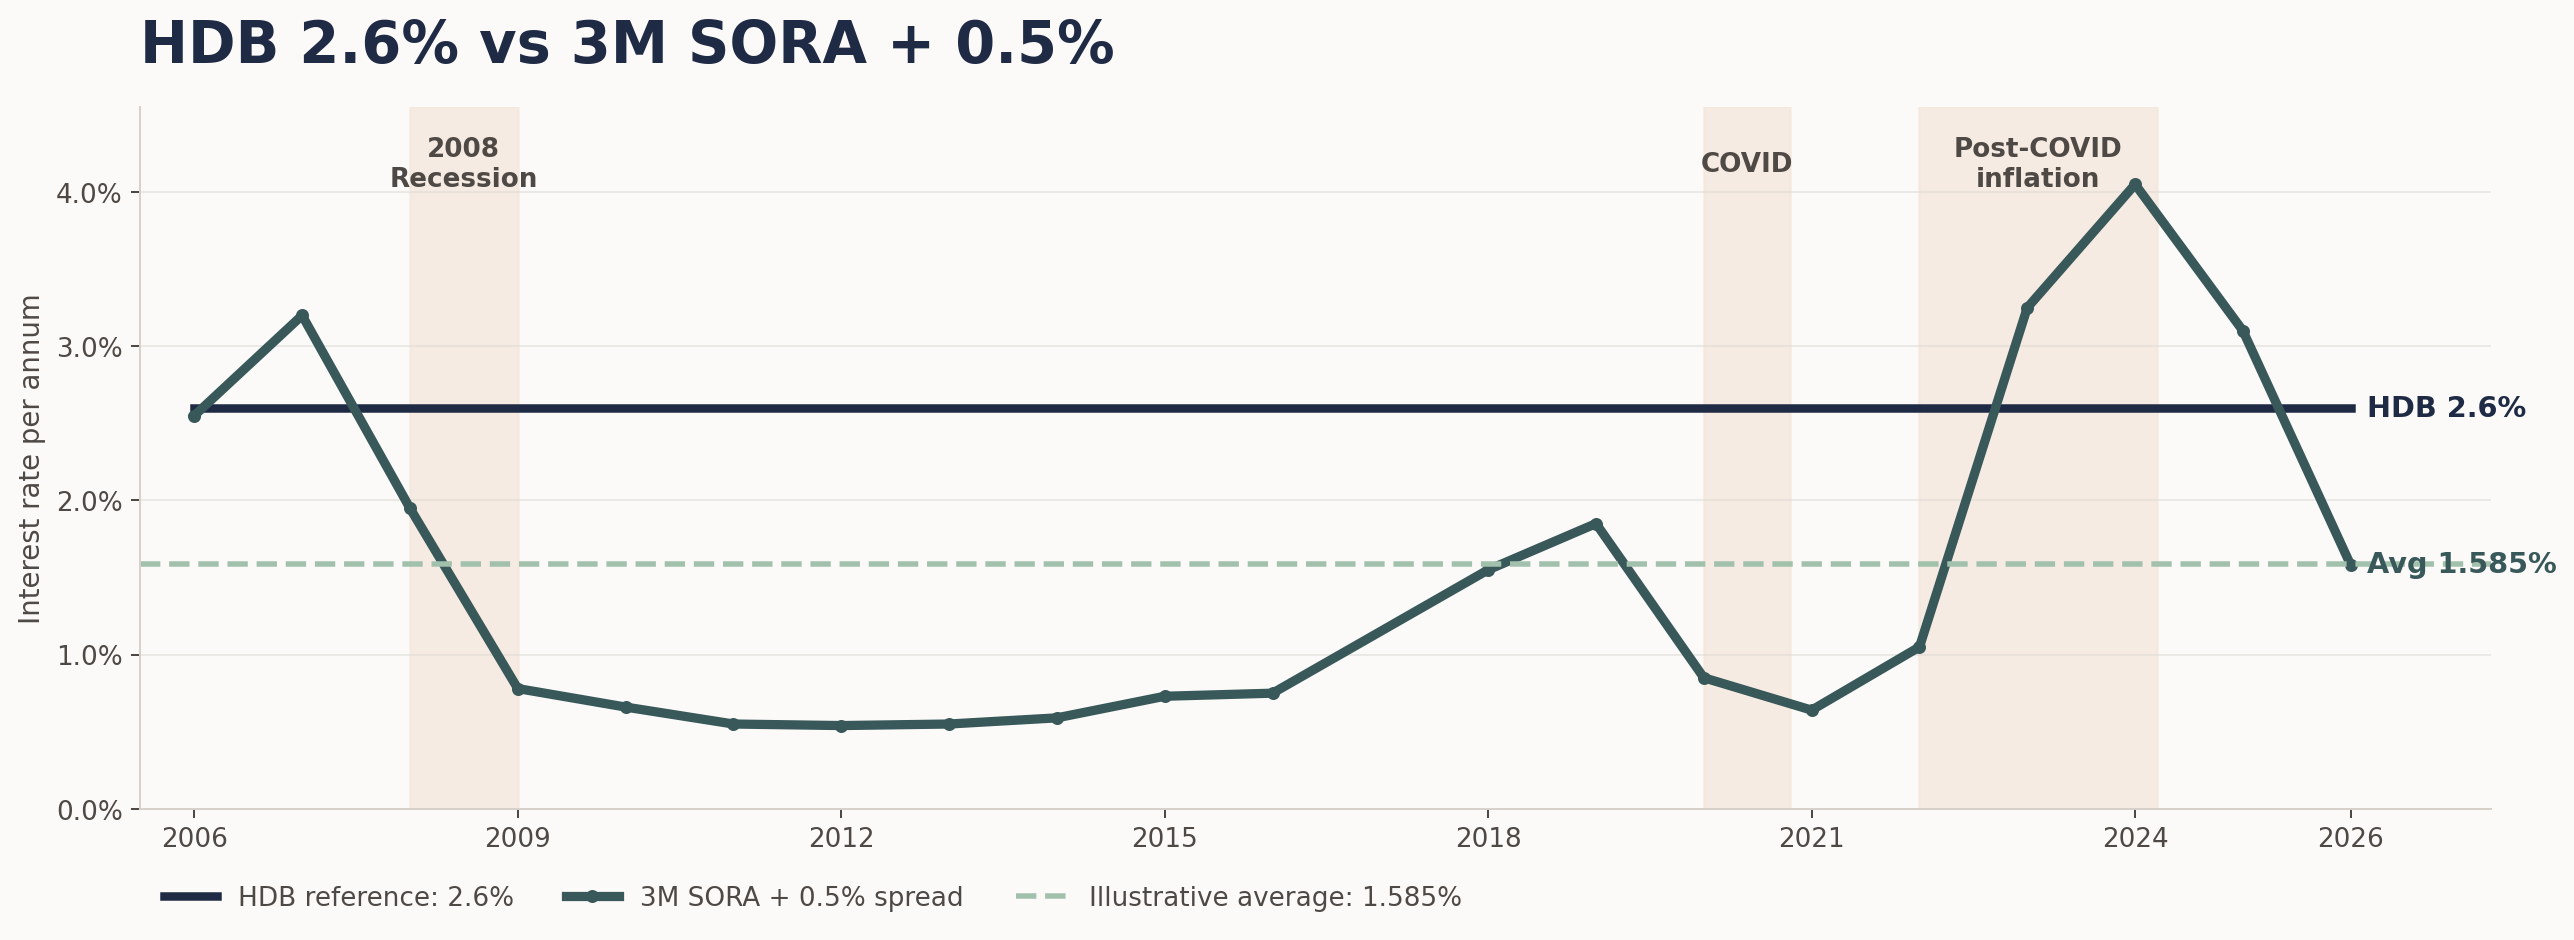
Chart comparing HDB rate reference versus SORA-linked bank loan path

This chart uses a simplified S$500,000 loan over 25 years and compares the long-standing HDB reference against an illustrative bank-loan path based on average 3M SORA plus a 0.5% spread. Even after including rough recession and inflation periods, the long-run average in this illustration still comes in lower than 2.6%.

What this really meansLower rates do not magically shorten your tenure by themselves if you keep the same loan structure. The savings usually show up in lower total interest and lower monthly instalments.
The real-life questionNot every borrower should automatically switch. The real question is whether the rate path, lock-in, flexibility and risk all suit your own situation.
Compare my HDB vs bank options

We do not take commission from you. So what are you really paying for?

Homeowners comparing mortgage advice and fees

A common myth is that getting mortgage advice means paying someone extra. In many mortgage-broker arrangements, the borrower does not pay a direct advisory fee. The key question is not “Will I be charged?” but “Will I get a clearer shortlist that actually fits my case?”

Typical client feeS$0 direct fee
Why people use brokersSpeed + clarity
Main valueShortlist that fits
What matters mostIndependent guidance can save time and reduce decision fatigue, especially when different banks suit different borrower profiles.
What to ask insteadAsk how the shortlist was built, what trade-offs are being made, and whether a recommendation fits your property, income profile and future plans.
Help me compare fitted options

Why rushing to pay off your loan might leave you worse off.

Homeowners comparing mortgage paydown and investing

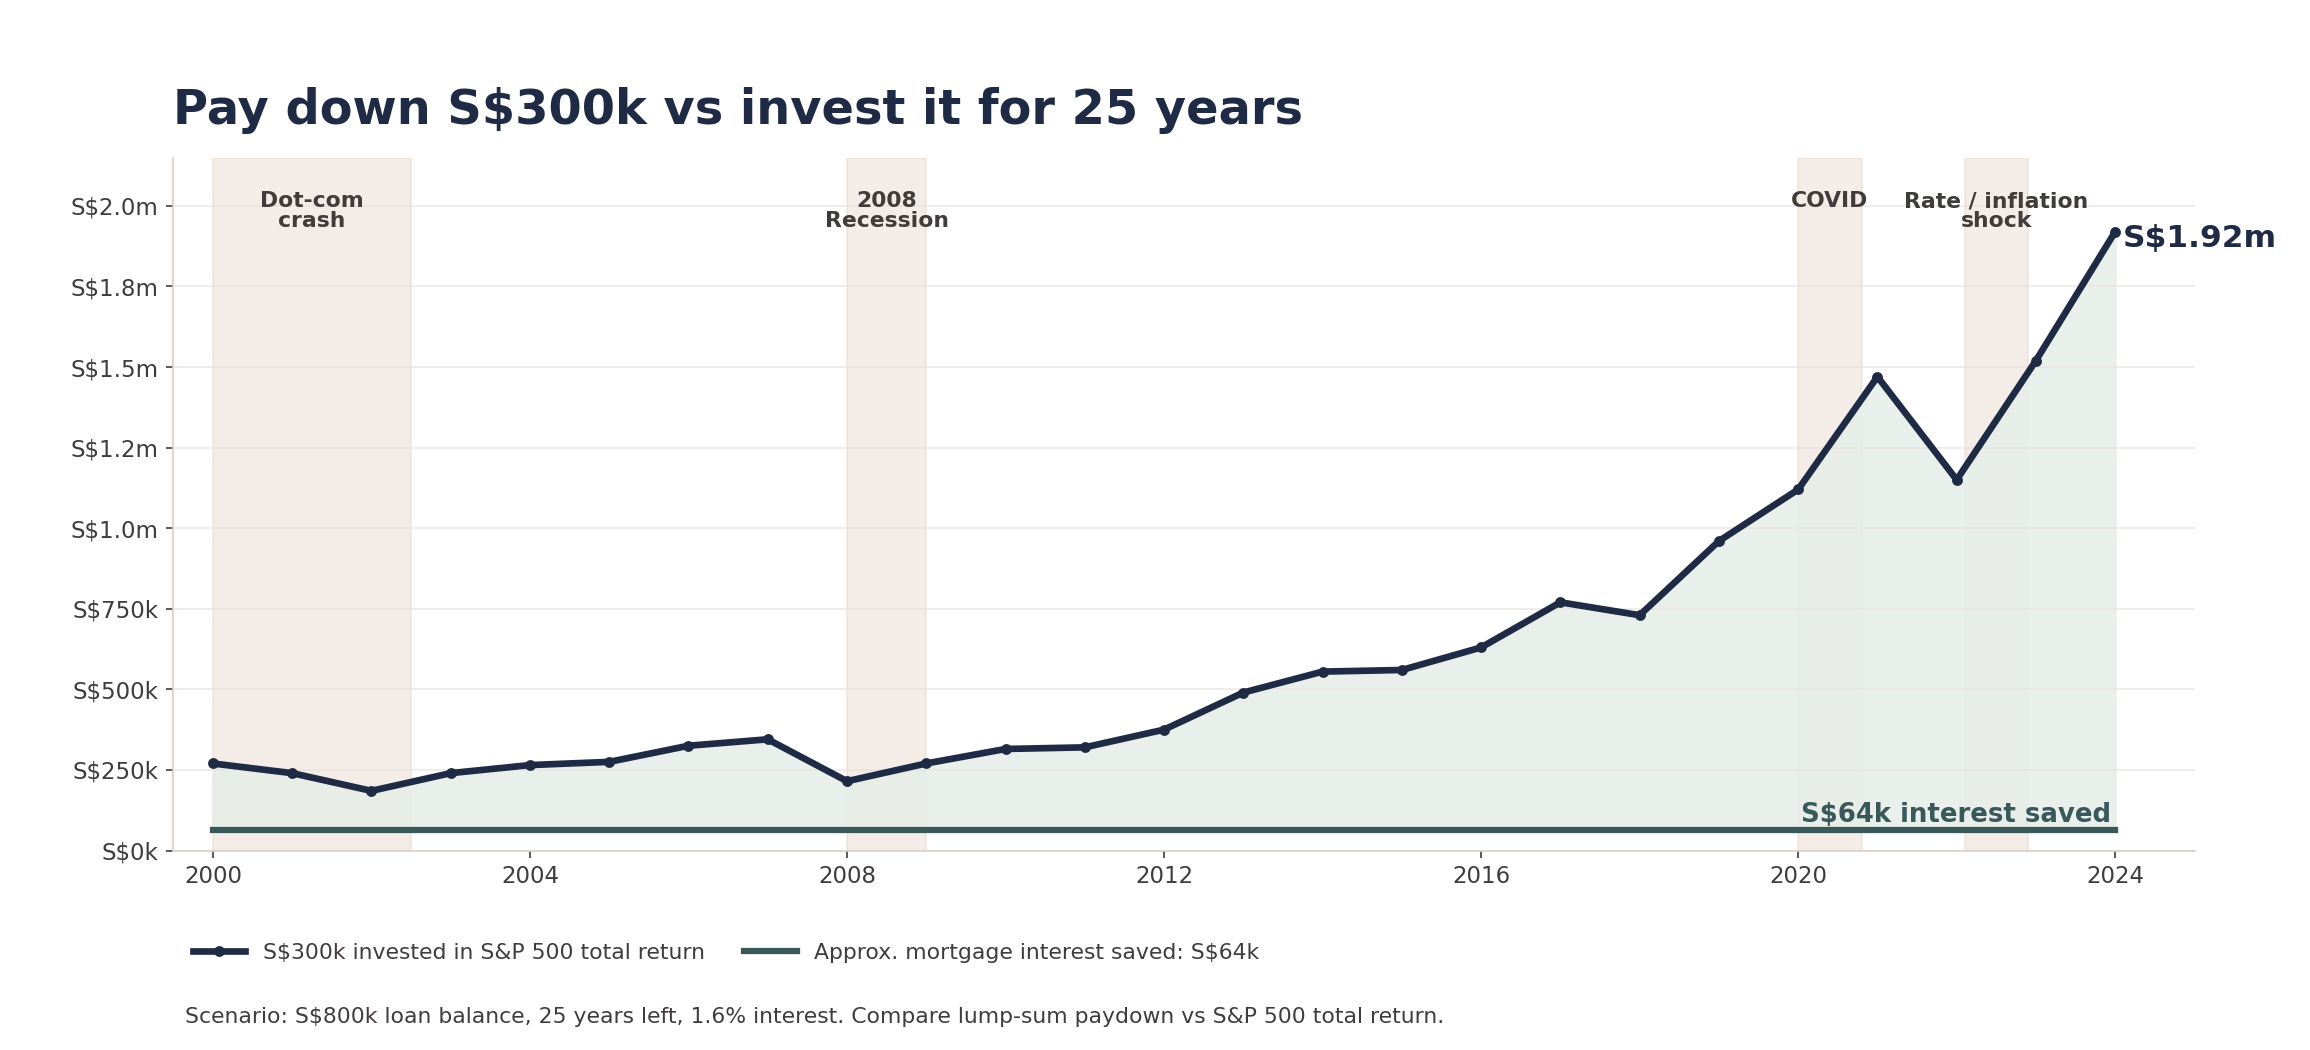
Some homeowners want to clear their loan as quickly as possible. That instinct is understandable. But if your mortgage is already at a relatively low rate, the better question may be: what if that same money stayed invested instead?

Illustrative loanS$800k @ 1.6%
Lump-sum choiceS$300k
25-year comparisonPay down vs invest
Chart comparing S&P 500 growth versus mortgage interest saved

This chart uses a simple thought experiment: instead of using S$300,000 to pay down the mortgage immediately, what if that money stayed invested in the S&P 500 with dividends reinvested? The chart uses historical total-return data to show how compounding can outweigh the mortgage-interest savings over a long enough period - even with major drawdowns along the way.

What to take awayBeing debt-free faster feels good. But mathematically, it is not always the best use of spare cash if the loan is cheap and the investment horizon is long.
What to think aboutThis only works if you can handle volatility, stay invested, and keep enough cash buffer. The best answer is behavioural as much as mathematical.
Show me the trade-off for my own numbers
Speak to a specialist

Speak to a human, not an AI.

Leave your details and tell us what you need. We will follow up and help you make sense of the numbers.